 vi
 en
Basket of Specialized Scores
Basket of Specialized Scores
- Value-added Services
- 15/10/2026
Basket of Specialized Scores (BoSS) is an advanced risk management solution jointly researched and developed by PCB and its partner CRIF. It comprises independent scoring models specifically designed and optimized for distinct credit product segments.
In the context of a rapidly changing financial market, applying a single traditional scoring model reveals significant limitations in sensitivity and accuracy when assessing specialized credit products (such as cash loans, credit cards, and consumer loans). BoSS effectively addresses these limitations through advanced analytical algorithms, enabling Credit Institutions (CIs) to:
- Optimize risk classification: Accurately assess the risk levels and potential of different customer segments across individual product lines.
- Automate and accelerate approvals: Reduce application assessment time, enhance competitiveness, and improve business efficiency.
- Scale safely: Accurately predict customer repayment trends, enabling CIs to reach new customer segments while maintaining effective control over non-performing loans.
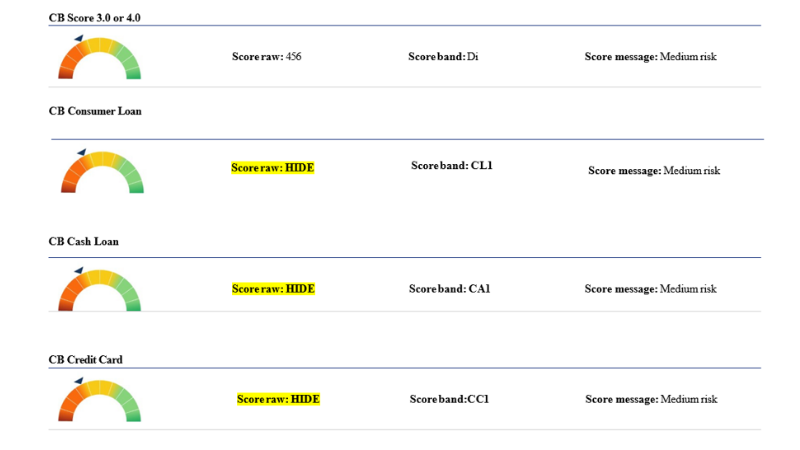
The BoSS solution provides four specialized scoring models, comprehensively addressing the credit assessment and portfolio development needs of CIs:
- Cash Loan Score: Specifically designed for the unsecured cash loan segment, where customers often have complex credit histories. The model enhances sensitivity in risk detection, optimizes the approval process, and effectively controls non-performing loan ratios.
- Credit Card Score: Specifically developed for credit card products, which are characterized by short-term and flexible borrowing. The model incorporates optimized variables to help CIs manage risks arising from uncontrolled spending behavior while accurately identifying customer segments with a strong ability to maintain consistent repayments.
- Consumer Loan Score: Focuses on loans used to purchase consumer assets and goods. The solution supports CIs in assessing customers’ short-term and long-term repayment capacity, managing portfolio risk, and significantly improving debt recovery rates.
- Propensity Score: Applies predictive modeling to forecast future borrowing trends rather than relying solely on historical credit data. The model enables CIs to effectively identify and engage new potential customer segments (including customers with limited credit histories) while maintaining risk levels within acceptable thresholds.